Guide · Central Florida
Does homeowners insurance cover water damage in Florida?
 24/7 response · IICRC certified
Short answer
Usually yes when the damage is sudden and accidental, like a burst pipe, a failed supply line or a water heater that ruptures. Usually no when the water came from outside flooding (that needs flood insurance) or from a slow leak that went on for weeks. Every policy is different, so read your declarations page and exclusions, and document the damage before repairs.
Key takeaways
- Sudden and accidental water damage is commonly covered.
- Flood from rising water outside is not covered by a standard homeowners policy.
- Many policies exclude leaks that continued for 14 days or more.
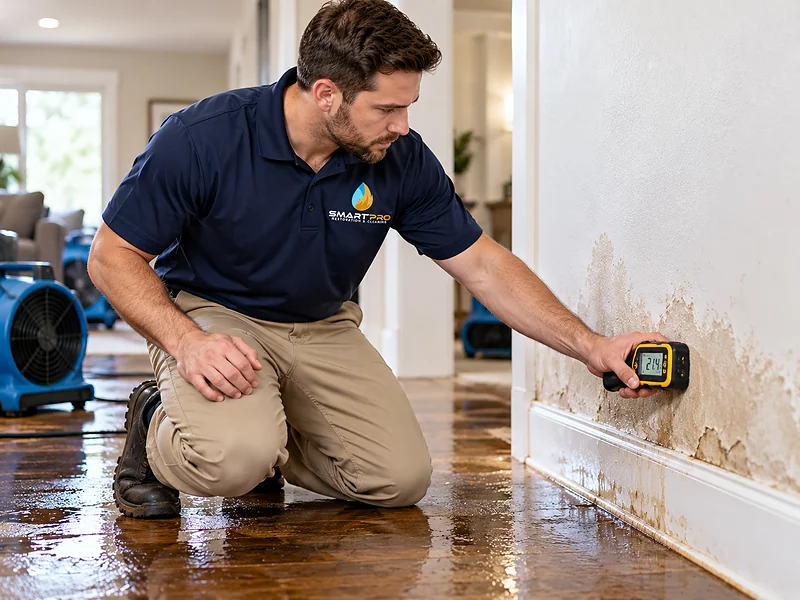
- Good documentation (photos, moisture readings, drying logs) is what gets claims paid.
What is usually covered
- Burst or frozen pipes
- Failed supply lines to toilets, sinks, ice makers and washing machines
- Water heater ruptures
- Accidental overflow from appliances
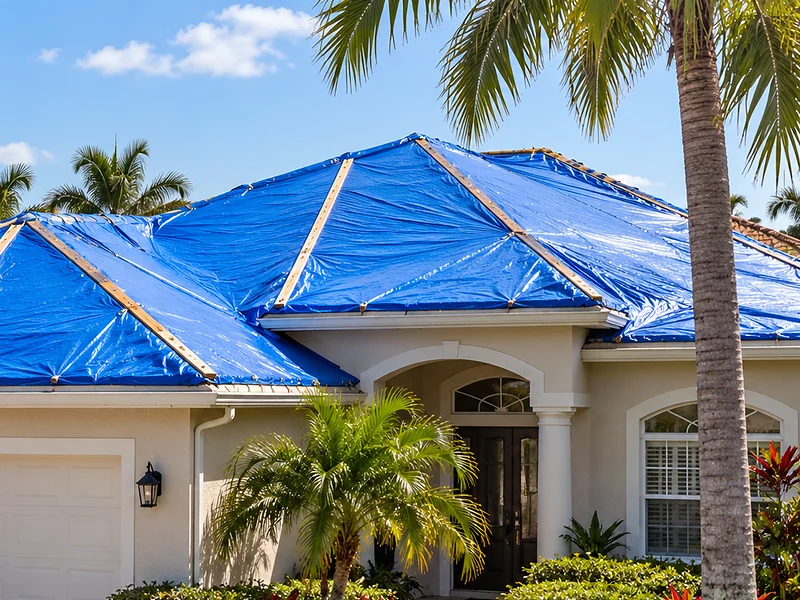
- Roof leaks caused by a covered event like wind damage
Policies commonly cover the resulting damage (drywall, flooring, cabinets) and the cost to dry the home. The broken part itself, like the old pipe, is often not covered.
What is usually not covered
| Situation | Typical treatment |
|---|---|
| Rising water from storms or flooding outside | Needs a separate flood policy (NFIP or private) |
| Slow leak over weeks or months | Often excluded as wear and tear or long-term seepage |
| Sewer or drain backup | Often requires a water backup endorsement |
| Mold from an old, unrepaired leak | Often excluded or capped |
What about hurricanes?
Florida homeowners policies usually carry a separate hurricane deductible, often a percentage of the dwelling coverage rather than a flat amount. Wind-driven rain through a damaged roof is typically handled under the windstorm coverage, while storm surge and rising water fall under flood insurance.
How to give your claim the best chance
- Stop the water and prevent further damage right away.
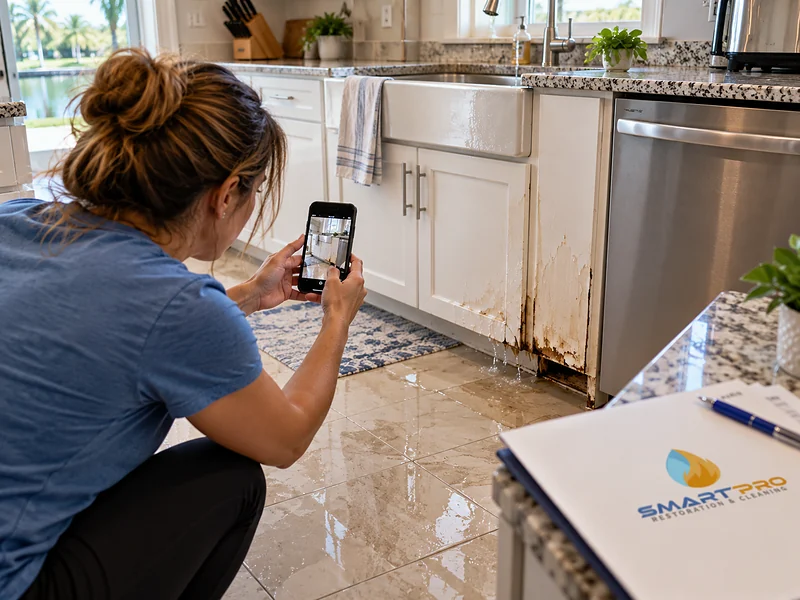
- Photograph the source and every affected room before cleanup.
- Report the claim promptly and write down the claim number.
- Keep receipts for anything you buy and for emergency services.
- Use a restoration company that provides moisture readings and daily drying logs.
Smart Pro and your claim
We are a restoration contractor, not a public adjuster or attorney. We document the damage, send the photos, readings and scope to your adjuster, and meet them on site if you want. Questions about your coverage itself should go to your insurer or a licensed professional.
Frequently asked questions
Do I have to use my insurance company's preferred contractor?
No. In Florida you can choose your own contractor.
Is mold covered after water damage?
When mold results from a covered, sudden water loss and is addressed quickly, many policies cover it, sometimes with a limit. Mold from long-term moisture is often excluded.
Does homeowners insurance cover flooding from a hurricane?
Not rising water. Storm surge and flooding need flood insurance. Wind and wind-driven rain damage through a damaged roof usually fall under the homeowners policy, subject to the hurricane deductible.
Related services
Water Damage Restoration
Burst pipes, AC leaks, water heater failures and flooding. Extraction, structural drying and repairs.
Learn more →
Storm & Hurricane Damage
Hurricane, tropical storm and wind damage: tarping, water removal, drying and rebuild.
Learn more →Insurance Claims
How the claim process works and what we document.
Learn more →